Expert Financial Advisor Reveals Insider Tips for Navigating Car Loans
Interviewer: Good day, fellow readers! Today, we have the pleasure of speaking with an expert in the field of car loans. Our guest is a financial advisor who will be shedding light on this topic for us. Welcome!
Financial Advisor: Thank you! It’s great to be here.
Interviewer: To start things off, could you provide our readers with a brief overview of what a car loan is?
Financial Advisor: Certainly! A car loan is a form of financing that allows individuals to purchase vehicles without having to pay the full amount upfront. Instead, they can borrow money from a lender and then repay it over an agreed-upon period through monthly installments.
Interviewer: That sounds convenient. How does one go about obtaining a car loan?
Financial Advisor: The process typically begins by researching different lenders and loan options available in the market. It’s essential to compare interest rates, terms, and conditions offered by various institutions before making any decisions.
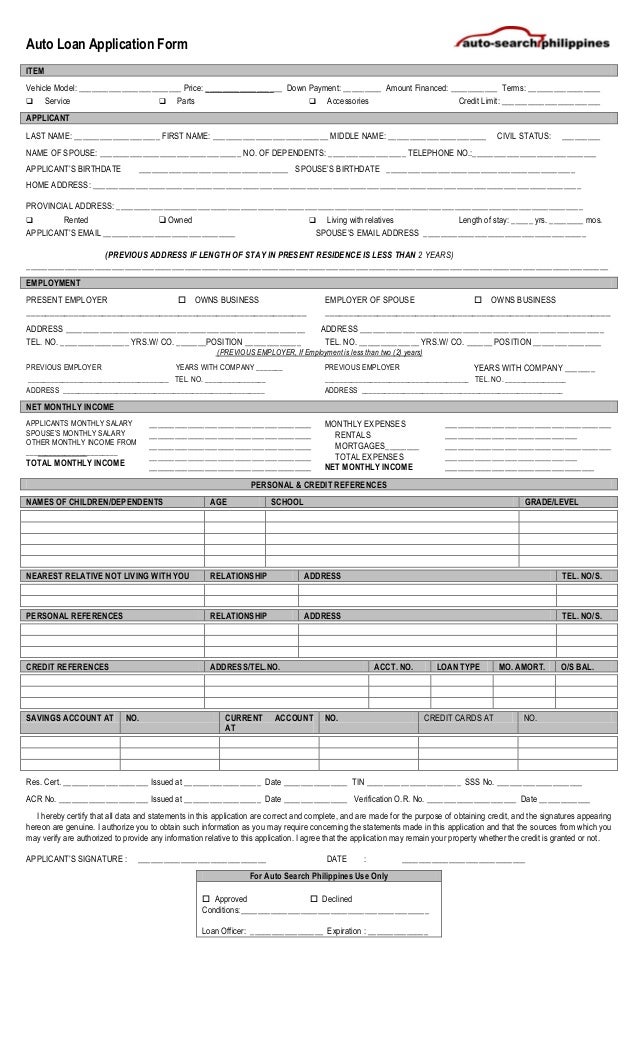
Once you’ve chosen your preferred lender or financial institution, you’ll need to submit an application for pre-approval. This involves providing personal information such as income details, employment history, credit score, and other relevant documents.
After submitting your application and supporting documents, the lender will evaluate your eligibility based on factors like creditworthiness and debt-to-income ratio. If approved, they will offer you loan terms outlining the borrowing amount limit and repayment schedule.
Interviewer: What are some key factors applicants should consider when applying for a car loan?
Financial Advisor: There are several crucial factors that applicants should keep in mind:
1. Credit Score – Your credit score plays a significant role in determining your eligibility for favorable loan terms. Maintaining good credit can help secure lower interest rates.
2.Income Stability – Lenders often prefer borrowers who have stable employment history and consistent income streams since this increases their confidence in timely repayments.
3.Down Payment – Providing a substantial down payment can help reduce the overall loan amount, making it easier to repay in the long run.
4. Loan Term – Choosing an appropriate loan term is essential as it affects monthly payments and interest rates. Longer terms may have lower monthly installments but result in higher overall interest payments.
5. Interest Rates – Comparing interest rates offered by different lenders is crucial in finding the most affordable option. Even a small difference in rates can significantly impact your total repayment amount.
6. Hidden Costs – It’s important to be aware of any additional fees or charges associated with the loan, such as processing fees or early repayment penalties.
7. Insurance Requirements – Most lenders require borrowers to have comprehensive car insurance for the duration of the loan term, so it’s vital to consider this additional expense.
Interviewer: Thank you for those insights! What are some common mistakes people make when applying for a car loan?
Financial Advisor: One common mistake is not shopping around enough for different lenders and settling on the first one they come across. By exploring various options, borrowers can potentially find better interest rates or more flexible terms that suit their financial situation.
Another mistake is not thoroughly reading and understanding all aspects of the loan agreement before signing it. Failing to do so may lead to unexpected surprises like hidden fees or unfavorable conditions down the line.
Additionally, some individuals underestimate their budgetary constraints and take on loans that they struggle to repay comfortably each month. It’s crucial always to consider your ability to meet monthly repayments without compromising other essential expenses or savings goals.
Interviewer: Excellent advice! Are there any specific tips you would offer our readers regarding car loans?
Financial Advisor: Absolutely! Here are some tips:
1.Evaluate Your Budget – Before committing yourself to a car loan, assess your current financial situation carefully.
2.Save for a Down Payment – Saving up for a down payment will help reduce both your monthly payments and overall debt burden.
3.Consider Pre-Approval – Obtaining pre-approval from a lender can help you understand your borrowing capacity and simplify the car shopping process.
4.Avoid Extending Loan Terms – While longer loan terms may seem appealing due to lower monthly payments, they often result in higher overall interest paid. Try to opt for shorter terms whenever possible.
5.Pay Attention to Interest Rates – Even a small difference in interest rates can have a significant impact on your repayment amount. Always try to secure the lowest rate available.
6.Understand Insurance Requirements – Familiarize yourself with insurance requirements imposed by lenders and consider how they will affect your overall expenses.
7.Seek Professional Advice – If you’re unsure about any aspect of the car loan process, don’t hesitate to consult with a financial advisor who can provide personalized guidance based on your specific circumstances.
Interviewer: Thank you once again for sharing your expertise with us! Do you have any closing thoughts?
Financial Advisor: It was my pleasure! I’d like to emphasize that obtaining a car loan is not just about getting the best deal but also understanding its long-term implications on your finances. By carefully considering all aspects of the loan agreement, making informed decisions, and structuring repayments within your means, you’ll be better equipped to enjoy both the ride and financial stability!
Interviewer: That’s sound advice indeed. Thank you so much for joining us today!
Financial Advisor: You’re welcome! It was my pleasure being here.