Credit Scores 101: Mastering the Basics for a Strong Financial Foundation
Credit Scores 101: Understanding the Basics
As a modern blacksmith, it is important to have a good understanding of credit scores. A credit score is a numerical representation of your creditworthiness, which lenders use to assess whether you are likely to pay back your debt on time.
There are three main credit bureaus in the United States that calculate and report credit scores: Equifax, Experian, and TransUnion. Each bureau uses its own algorithm to determine your score, but all three consider similar factors when calculating your score.
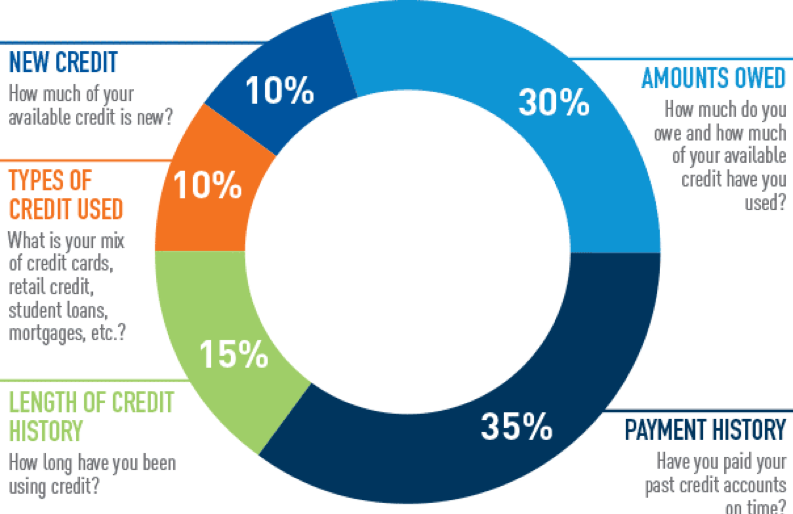
The most important factor that affects your credit score is payment history. This includes whether you have missed payments or made late payments in the past. Late payments can stay on your record for up to seven years and can significantly lower your score.
The second most important factor is the amount of debt you currently owe. This includes both revolving debt (such as credit card balances) and installment loans (such as car loans). Lenders want to see that you are using credit responsibly and not overextending yourself financially.
The third factor that affects your credit score is the length of your credit history. The longer you have had accounts open and in good standing, the better it looks on paper. It’s worth noting that closing an account does not erase its positive influence on your overall length of history; it may even hurt it slightly if there was any outstanding balance left unpaid.
Another key factor affecting overall health of one’s finances is utilization rate – this measures how much revolving debt one has compared with their total available revolving line-of-credit they posses across all active accounts combined together – ideally this should be less than 30% at any given time else it might indicate financial stress or over-reliance upon revolving debts like cards etc..
Finally, new inquiries into your credit can also affect your score negatively because they may signal potential financial instability or too many hard pulls within short period indicating overspending or desperation for funds.
Now that we know what factors affect your credit score, let’s talk about what a good credit score looks like. Generally, a score above 700 is considered “good,” while a score above 800 is considered “excellent.” A lower score means you may have trouble getting approved for loans or credit cards, and if you are approved, you may not get the best interest rates available.
If your credit score needs improvement, there are several things you can do to boost it. The first step is to make sure all of your payments are made on time going forward – late payments can be especially damaging to your overall health of finances as well as reputation in the eyes of creditors who might see this as indicative of lack in responsibility with money management skills.
The second step is to pay off any outstanding debts that are negatively affecting your utilization rate – ideally one should aim for keeping total revolving debt within 30% of their available line-of-credit at any given time but lower values would indicate better financial stability and discipline.
Another way to improve your credit score is by increasing the length of your credit history which will take some patience since it involves waiting over time and building slow yet steady progress towards bigger financial goals.
You could also consider applying for new lines-of-credit such as secured loans or secured lines-of-credit which would help diversify types of accounts held under one’s name while also boosting overall usage across different account-types (ie: having both revolving debts like cards and installment loans), however opening too many new accounts simultaneously might lead to hard inquiries which could negatively impact scores temporarily till these fall off after two years’ time passes by.
In summary, having a good understanding of how credit scores work can help modern blacksmiths maintain healthy personal finances and access funding when they need it most. By paying attention to payment history, debt levels, length of history, utilization rate and avoiding too many hard inquiries, you can take control of your credit score and build a strong financial foundation for your business.