From Ancient Times to Modern Day: The Evolution of Credit Scores
Improving Your Credit Score: A Historical Perspective
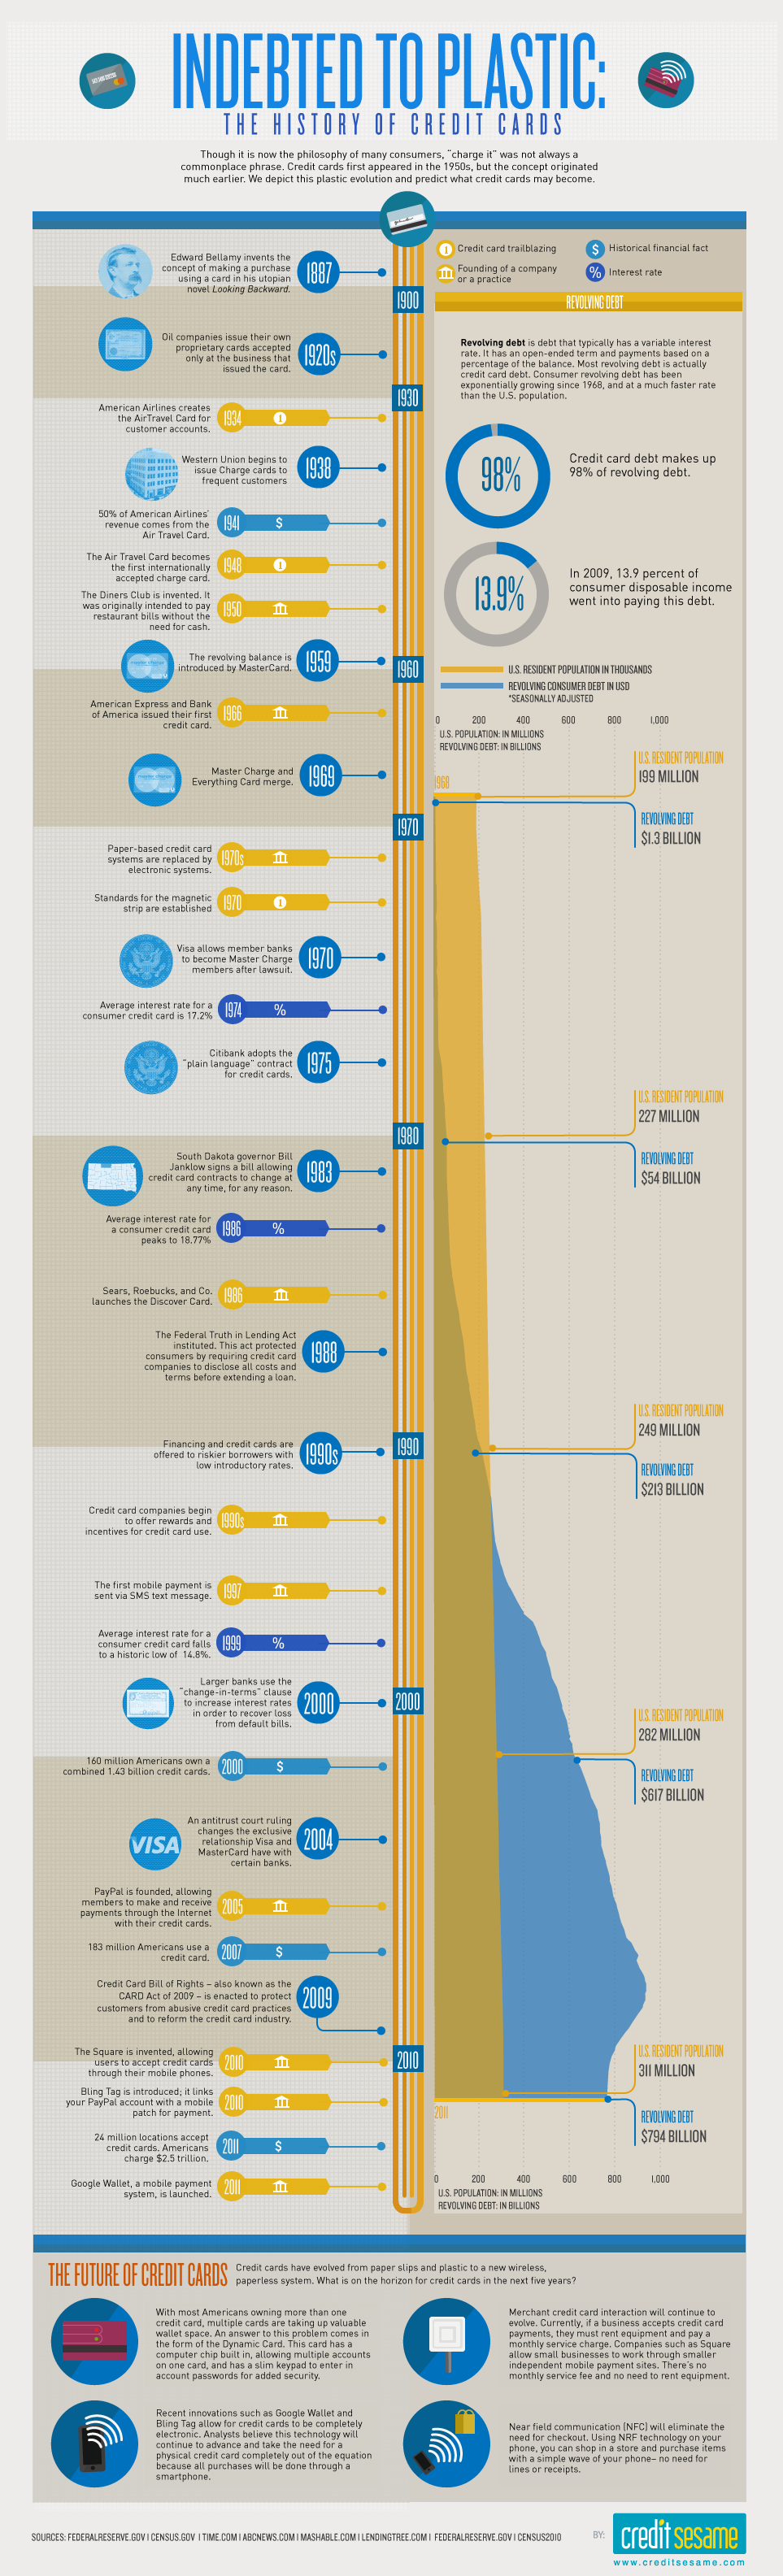
Credit scores have become an integral part of modern society. They are used by lenders to determine the creditworthiness of individuals seeking loans, mortgages or credit cards. However, the practice of using credit scores is not a new one. It has been around for centuries and has evolved over time.
In ancient times, lending was done on a personal basis. People would lend money to their family members, friends or acquaintances based on trust and reputation. The lender would assess the borrower’s character and ability to pay back the loan before making a decision.
As societies became more complex, lending became more formalized and centralized. Banks emerged as institutions that provided loans on a large scale. To mitigate their risks, they needed a way to assess the creditworthiness of borrowers objectively.
The first credit bureaus were established in Europe in the late 19th century. They collected information about people’s borrowing habits from merchants and other sources and created reports that were sold to subscribers such as banks and businesses.
In the United States, the use of credit scoring started in earnest in the 1950s when Fair Isaac Corporation (FICO) introduced its first scoring model. FICO scores range from 300 to 850 with higher scores indicating better creditworthiness.
Today, there are three major credit reporting agencies – Equifax, Experian and TransUnion – that collect information about consumers’ borrowing habits such as payment history, outstanding debts and length of credit history. This information is used to calculate their credit scores which determine their eligibility for loans at favorable interest rates.
If you have a low score or no score at all due to limited borrowing history you can take steps towards improving your rating:
1) Pay your bills on time – Late payments can have a significant negative impact on your score.
2) Reduce your debt – High levels of outstanding debt will negatively impact your score.
3) Keep your credit utilization ratio low – This is the amount of credit you are using compared to the amount available. It is recommended not to exceed 30% usage.
4) Monitor your credit report regularly – Check for errors and mistakes that could be affecting your score.
5) Avoid opening too many new accounts – Opening multiple accounts in a short period can indicate financial distress and negatively impact your score.
In conclusion, while our modern-day approach to lending may appear very different from ancient times, it still relies on trustworthiness and reputation. The use of credit scores has evolved over centuries but remains an essential tool for lenders. Improving one’s score takes time and effort but can lead to better access to loans at lower interest rates which will ultimately improve one’s financial position.