7 Student Loan Repayment Options to Manage Your Debt Stress-Free
Student Loan Repayment Options
The cost of higher education has risen dramatically over the years, and many students are left with a significant amount of student loan debt after graduation. Student loans can be a burden for recent graduates who need to start their careers and may not have the means to pay back their loans immediately. However, there are several repayment options available that can help graduates manage their student loan debt.
1. Standard Repayment Plan
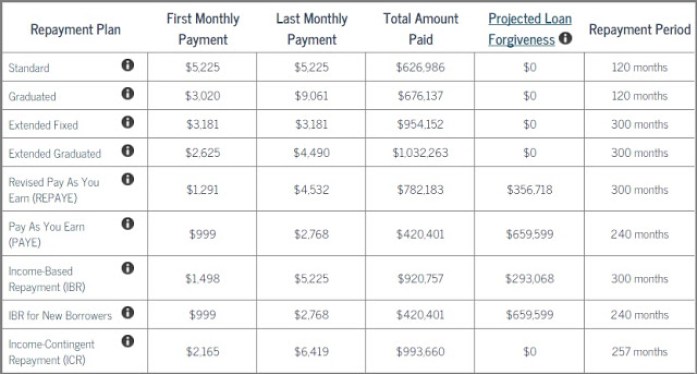
The standard repayment plan is the most common type of student loan repayment plan. Under this plan, borrowers make fixed monthly payments for ten years until the loan is paid in full. This option is suitable for those who have steady jobs and can afford to make the same payment every month.
2. Graduated Repayment Plan
A graduated repayment plan allows borrowers to make lower payments at first and then gradually increase them over time. The idea behind this program is that borrowers’ income will increase as they gain more experience in their field, making it easier to pay off their loans later on.
3. Income-Driven Repayment Plans
Income-driven repayment plans are designed for those who cannot afford standard or graduated payments because of low income or job loss. These plans allow borrowers to make payments based on their income level, ensuring that you won’t default on your loans if you’re struggling financially.
There are four types of income-driven repayment plans: Income-Based Repayment (IBR), Pay As You Earn (PAYE), Revised Pay As You Earn (REPAYE), and Income-Contingent Repayment (ICR). Each plan has its own eligibility requirements, but they all calculate your monthly payment based on your discretionary income.
4. Public Service Loan Forgiveness Program
If you work in public service organizations such as government agencies or non-profit organizations, you may qualify for public service loan forgiveness programs like PSLF (Public Service Loan Forgiveness) program which enables qualifying borrowers working in public service to have their remaining loan balance forgiven after making 120 qualifying payments.
5. Student Loan Consolidation
Another option is student loan consolidation, which enables borrowers to combine multiple federal loans into a single loan with a fixed interest rate and payment term. This option can simplify the repayment process by reducing the number of monthly payments.
6. Private Refinancing
Private refinancing is an alternative option for graduates who want to consolidate their loans and lower their interest rates but does not offer federal benefits such as income-driven repayment or forgiveness programs. Private refinancing may lead to lower monthly payments, but it’s important for borrowers to be aware that they will lose access to some of the benefits offered under federal student loans.
7. Deferment or Forbearance
Deferment or forbearance allows you temporarily pause your student loan payments due to unemployment, financial hardship, or serving in military service without accruing additional interest on your loans. However, keep in mind that this only applies during the deferment period and you’ll still be responsible for paying off your debt over time.
Final Thoughts:
Having a large amount of student debt can be stressful and overwhelming; however, there are several options available that can help make managing your debt more manageable. It’s essential for recent graduates to consider all these options carefully before selecting one plan over others that suits them best based on their current financial circumstances and future goals while keeping in mind consequences like losing access to some of the benefits offered under federal student loans if opting for private refinancing.
Regardless of which route you choose when repaying your student loans, remember that being proactive about managing your finances today will pay off tomorrow!